'Big Short' Investor Explains How the AI Bubble Will Burst
Now Playing
'Big Short' Investor Explains How the AI Bubble Will Burst
Transcript
1311 segments
Let's just imagine that open AI fails.
Could happen.
>> The host of the real Eisman playbook
podcast.
>> I don't know about you, but I know that
I don't have a hundred billion dollars
to spend on building data centers.
[music]
>> You may know our next guest from the Big
Short.
>> Your character.
>> You had to work that in there, didn't
you?
>> I did have to.
>> Do you like being described [music] that
way? I think it's going to be on my
tombstone.
>> The whole United States of America would
go into a recession overnight. Oh,
yikes. Okay,
>> Mr. Anders.
>> Well, I'd have said you're out of your
mind.
>> Yeah, you're insane. to get my
programming to impersonate a DT.
>> This industry, despite all the hundreds
of billions of dollars [music] that's
been spent on it, has
>> join us right now is Steve Eisman.
>> Let's bring in Steve Eisman.
>> Steve, welcome back. You are known for
spotting a bubble before anyone else
does. Michael Lewis wrote a whole book
on it. So, my first question to you is,
where on earth are we in AI right now?
There was a great movie with uh Sean
Conre where he played this I can't
remember the name of Finding Forester.
And I remember the young character asks
him a very complicated question and his
response is as he's eating soup he goes,
"It's not exactly a soup question. It's
a complicated question." [laughter] I
never forgot that line. I thought it was
one of the best lines in in the history
of movies. It's not a soup question.
>> Not exactly a soup question, is it?
>> This is how I look at it. The
concentration
risks here are all inspiring, you know.
So, you take a step back and you and
someone said to me, why don't you
analyze this software company? Forget
about what it does. It's a software
company, an established software
company. And if it turned out that the
company had thousands of customers, that
would be great. If it turned out the
company only had two customers, you'd
say, "I don't want to invest in that
because if something bad happens to one
of those customers, this company is is
dead." There's something of that going
on in the whole AI story. So, let's
start just with Nvidia. So, Nvidia, God
bless them, and I own the stock, okay?
When they reported a few weeks ago, I
think the revenue growth was like it was
like 110%.
>> It's a lot. So, so let's just let's just
take a step back just for a second and
say to ourselves, wait a minute. The
largest company on planet Earth just had
forget about earnings growth, which was
great, too. Just revenue revenue growth
of over 100%. Like, that's insane. So,
that would say the AI story is great
until you read the 10 Q, which came out
that night. And I'm going to impress
your viewers by saying if they look at
it and they go to Note 7.
>> Oh, okay.
>> Okay. Yeah. Note 7 says that 70% of
Nvidia's accounts receivable as of the
end of July came from five customers.
>> Warning flag. Not the end of the world.
Warning flag. Now, let's go to the
hyperscalers. You're talking about
Google, Meta, Amazon, Microsoft, and
let's throw Oracle in for good measure.
massive companies spending massive
amounts of money by buying Nvidia's
chips and everything else under the sun.
70%
of their AI revenue which equals
something like 25 to 30% of their entire
cloud revenue
comes solely from anthropic and open AI.
>> Right?
>> Let me just let me just say it again so
your viewers get it. If you look at
leave out Oracle for a second,
Microsoft, Amazon, [snorts]
Google, 70% of their AI revenue, which
is equivalent to 25 to 30% of their
total cloud revenue is just from
anthropic and open AI. If you go to
Oracle, Oracle puts out a data point
called RPO,
which is basically a form of backlog.
when they reported earnings last year in
October for their August quarter, their
RPO went from like 150 billion to like
400 billion
>> in 3 months.
>> It was a massive jump.
>> It was massive jump. I mean, people went
insane. Yes.
>> And the stock went crazy.
>> The stock went crazy. It went from 230
>> to 330 like in two days.
>> Yeah. And then some of the cellite
analysts who are very good who did some
digging came out with reports that said
50% of that RPO is just from open AI.
>> Now now today
Oracle is is over 600 billion and it's
still like 50% is from open AI.
Basically 50% of future revenue of
Oracle is from a company that loses
money like crazy.
>> Well that's what I was going to ask you.
Maybe you can explain how this works.
But from my perspective, I don't
understand where this money is coming
from.
>> We're coming to that. Okay. Let me let
me just finish the let me just finish
the chain. Yeah.
>> So now we come all the way now to Oric
to Anthropic and Open AI. And my view is
the entire chain from Nvidia to the
hyperscalers all the way down the whole
chain rests on the future health and
growth of enthropic and open AI because
they're creating the commitments to the
hyperscalers. If they don't grow and
have the money to pay for those
commitments, well then the whole chain
slows.
>> Yeah.
>> So that's the risk. I would say between
the two probably Open AAI is the weaker
entity. But it's not clear because
really we really don't have enough
numbers. The only thing we do know
because the Wall Street Journal reported
this, so I'm assuming it's true. Open AI
had I something like six and a half
billion
in revenue
in the second quarter of this year.
>> Okay.
>> Anthropic was at 11 plus
>> but this is just revenue
>> just revenue.
>> Okay.
>> Open AI lost something had cost of
something like 12 billion. So the way
the math worked was in three months Open
AI Open AI's revenue went up a billion
and its cost went up three billion which
which we like to say is upside down.
>> You want the reverse not the former they
want the other way to go.
>> Great business model.
>> And and their revenue grew 18% in 3
months whereas Anthropic's revenue grew
over 100% in three months. So they're
the weaker company at this point. That
could that could change. My my only
point is that this whole this whole
industry makes me nervous because let's
let's just imagine that open AI fails
>> could happen.
>> The whole like the you know the whole
United States of America would go into a
recession overnight if this would and
now eventually there'll be a lot more
diversification and there'll be a lot
more companies but that's going to take
time. So you know within the next year
or so those companies have got to stay
healthy. That's where I think we are. So
there's a concentration risk.
>> There's a massive concentration risk.
>> And that brings me to the to the
question I I was asking before. My
understanding is that well we just spoke
about these uh open AI and anthropic are
not making money. They're losing money.
>> Excuse me. To say that they're losing
money would be kind. They bleed money.
>> What's the nicest way?
>> They lose a lot of money.
>> We're pre Yeah, we're pre-p profofit,
right? Prepit. [laughter]
Something like that. They they make
money if you exclude all costs. Yeah,
exactly. That's how they like to think
about it.
>> That's that's we should start reporting
that metric.
>> Yes, I we [laughter] should.
>> Um so where where does the money come
from?
>> Well, that's actually a very interesting
question. I had thought that most of the
company most of the money was coming
from venture capital and that h happens
to be not true. Most of the company is
coming from Amazon, Google, Microsoft
and Nvidia investing in these companies
and SoftBank.
>> Okay. So, taking equity stakes in
>> taking equity stakes. They raise capital
and those guys have ponyed up money.
Whether they want to continue to pony up
money, I don't know.
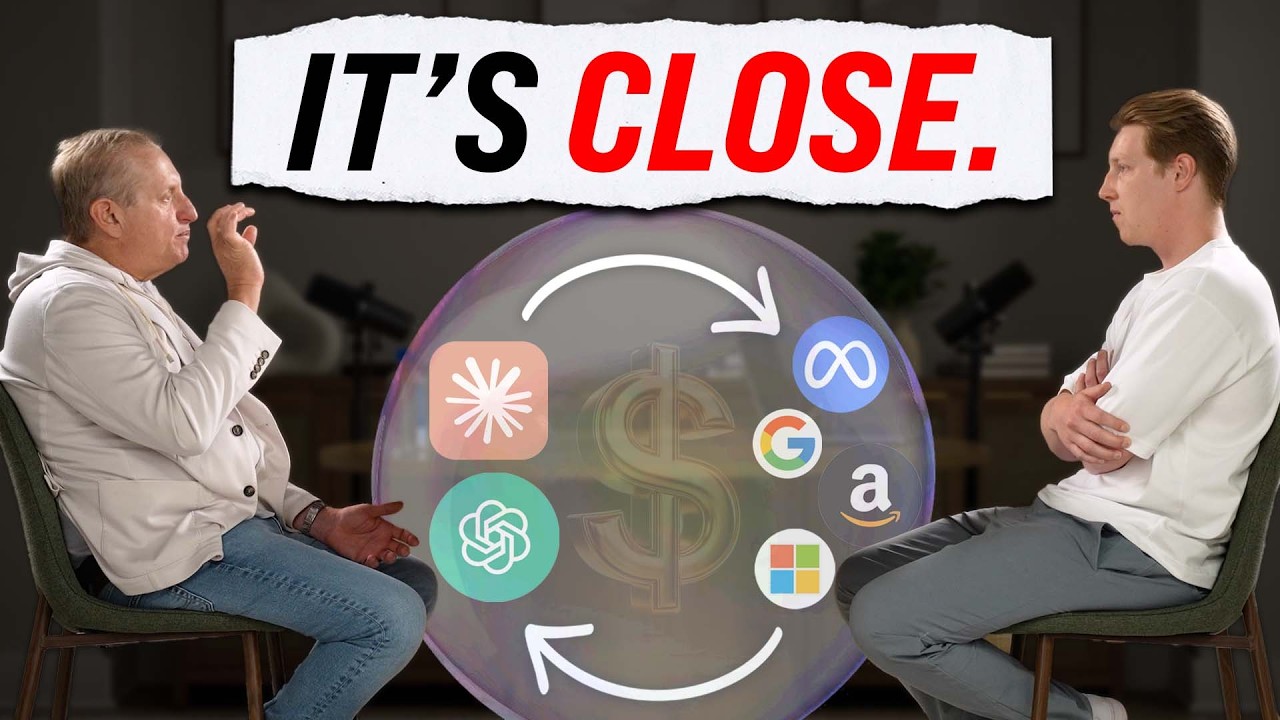
>> That sounds like a circle. It sounds
like money or commitments are going one
way and then commitments are coming back
the other way.
>> Yeah, it does have that tendency, does
it? This kind of reminds me of the It's
actually a scene from the big short uh
with your character.
>> You had to work that in there, didn't
you?
>> I I did have to work I remember you
saying, "Oh, it's kind of like CDOA and
then they put parts of that into CDOB
and those two put in CDOC."
>> There's some similarities obviously, but
in their defense, there is a circularity
to the financing. But as long as
anthropic and open AI keep growing very
very rapidly and people keep giving them
money, the chain will hold. It's if one
of those two companies really messes up
and pe people pull money or don't want
to invest it anymore that that's when
the chain doesn't hold. That that's
where the concentration risk problem
comes in. If the industry was much if if
this if if if I had said instead of 70%
of hyperscaler
AI revenue comes from anthropic and open
AI if that number had been 10%.
We'd be having an entirely different
conversation because there clearly there
are a lot more customers out there of
size. M. So that brings me to another
argument that I've heard you make on
your podcast and with your guests is
that if some
>> Let's just plug that podcast for a
second and call it the real Eisman.
>> Real Eman playbook. Yeah, absolutely.
It's very very good and it's gaining a
lot of traction. I think it comes down
to the authenticity of it.
>> Well, I appreciate that. I really enjoy
it. I think it's very very high.
>> My wife and I work on it
>> every day.
>> Both of you guys? I didn't realize. So
my wife is my partner in this and um so
she does god bless her all the editing.
>> Oh really?
>> This gave you an insight into into
things. So I I am a very linear thinker
>> which which the way I would define it is
one two three four five conclusion.
>> Got it?
>> And too often I write that way. So, I'll
write I'll do we have this thing called
the weekly rap which we put out Friday
where I sum up the week
>> and too often when I write it I'll I'll
I'll do one two three four five six and
and Valerie my wife who's who's the
editor will always say you buried the
lead again. Yeah.
>> And she'll flip it.
>> Ah okay.
>> And so because she says you know most
people never get to the bottom. you
know, people get your conclusions at the
bottom and it takes it takes 10 minutes
to get to the bottom. So, she so she
edits it and she runs the business,
>> right? Okay. That's cool. I didn't know
that. That's that's a little behind the
scenes. I like that.
>> Okay. Back back to back to AI train of
thought before I forget my train of
thought again. So going on from what
you're saying, if something happens to
OpenAI or Anthropic,
that's where the problems could be at
this moment in time when we've got the
concentration risk.
>> How do you see things like
Deep Seek's new model or Kimmy, what is
it called now? Kimmy,
>> best name in the biz.
>> Kimmy K3.
>> I like that. It just rolls up the
>> So this is where the the industry has, I
think, real weak business weakness.
Yeah, not not con let leave aside
concentration risk. That's its own risk.
Here's the business risk. There was
something going on for a while which is
called token maxing
which is where for lack of a better term
I work for a company [clears throat] and
I'm the I'm I'm a software engineer and
I've been told by management you're to
use AI 247 whether you need it or not.
>> Just do it.
>> Just do it. Right.
>> What happened was last year Open AI and
Anthropic were dramatically
undercharging for for their services.
Then they raised prices because they
they were so undercharging for the cost
of tokens. It was killing them,
>> right?
>> So they increased the prices that so
that the the customer was bearing more
of the cost of the token.
>> So you get people in once you got people
in raise the price.
>> Raise the price. Uber I think went blew
through its entire AI budget in like
three or four months.
>> Oh yikes. Okay.
>> Okay. And that this was some some other
company that I read about spent $500
million before they even knew they had
spent $500 million. So what's happened
is people have gotten a lot more
costconscious. Token maxing has gone
away and people are using these
openweight models a lot more. You don't
need a Cadillac for everything, you
know. So people will use um anthropic
and open AI as models only for the super
important tasks. Everything else they'll
use Kimmy K3 or or whatever. So what I
like to say about this is that this
industry despite all the hundreds of
billions of dollars that's been spent on
it has no moes.
>> There are no moes. This is you know
Google with its search until very very
recently that was a moat. I mean,
everybody used Google like I mean
>> 90%
>> 90% of planet Earth used Google and no
one even think about it
>> because because it was just better and
nobody could could approach it
>> you know here one day it's Gemini one
day it's chat GPT another day it's
Claude they they just rotate
>> and so well we'll come to it about my
conspiracy theory about the end of the
world
>> conspiracy theory all right so this this
dovetales into my conspiracy Okay. Okay.
>> So, as every as all your viewers know,
the world's going to end
>> some point. It has to
>> at some point it has to maybe it could
be five billion years from now or in a
couple of weeks.
>> Yeah. CNBC and Wall Street.
>> I I think this entire
AI is going to end the world is a
complete subtrauge.
>> Okay.
>> And what I think is really going on is
that these companies are nervous.
They're nervous that token maxing has
ended. They're nervous that there are no
moes. They're nervous that these they
these Chinese openweight models are
taking massive market share. So they're
manufacturing a hysteria which what
they're hoping for is for the government
to come in and regulate the industry and
they think that by manip they could
manipulate that regulation
to create a duopoly
>> so that will that the regulation will
create the moes. the regulation will say
no Chinese AI models. There's too big a
risk.
>> I see.
>> And then all all of a sudden there's a
moat. Yeah.
>> That didn't exist before
>> a legal barrier.
>> That's what I think is is is actually
happening here. So you think that's the
reason behind I cuz I've noticed Elon
he's always talking about it but
recently the uh anthropic CEO Dario
>> and they're also talking about slowing
down
>> slow and that that cannot be that cannot
be taken seriously because if you really
really really if you if I was Dario Modi
>> and I really really really thought
>> that my product is dangerous and I
really need to slow
I'd postpone my IPO.
>> You'd have to postpone your IPO.
>> You could just do take the steps.
>> Take a step back and and you know, I'll
fix fix what we need to fix and we'll
come back. Are they postponing their
IPO? No. You know, Elon Musk had a very
funny quote the other day where I think
he did on X where he said something like
um I'm going to paraphrase. I don't have
the exact This is some messed up 4D
chess where you're saying that the that
your product's going to end. Oh, and by
the way, how much can I allocate to you
for the IPO? [laughter]
>> Yeah.
>> You know, seriously, I I take people
seriously when they put their their
money at risk,
>> right?
>> You know, this this statement about a
slowdown is is just all part of this
hysteria that they're trying to
manufacture,
>> right? So they're aware that there may
not be moes and it kind of for for those
that don't know explain what you what
you mean we're talking moes specifically
in uh not hypers scale in the LLM
providers because the there I guess
there's still
>> the hyperscalers have moes
>> okay hyperscaler so so what's a moat
>> your grocery store doesn't have a moat
>> because somebody could open up a grocery
store across the street tomorrow
>> but there are some businesses that have
real moes real moes around them
>> like a competitive advantage.
>> It's but it's a competitive advantage
that is eternal or or at least very long
lasting like Nvidia makes GPUs.
>> Mhm.
>> Well, nobody else really makes GPUs.
>> That's a moat. certain software
companies have, you know, when if you're
Salesforce or Service Now, which are two
massive software companies, you your
product is embedded in the companies
that you service. Like like
>> those companies that use your your
product, [snorts] they've used it for so
long, they can't function without your
product.
>> Hard to switch away.
>> You try and get to try and switch out of
that is brutal.
>> Yeah,
>> that's a moat. There's no hyperscaler.
What's the moat? Well, I don't know
about you, but I know that I don't have
hundred billion dollars to spend on
building data centers.
>> Okay?
>> They just don't have it.
>> So, there is some moist.
>> So, that so just in terms of size and
money, I mean, there only certain
companies that can actually build data
centers.
>> They're just that expensive. LLMs, the
the creation of the models is expensive,
but there's so much competition
and there's no loyalty. Like, you know,
if you're a if you're a software
developer and you're using Claude, if
tomorrow another LLM shows up that's
better than Claude, you'll switch.
>> Y
>> you're you're switch there's no there's
you're not stuck.
>> That's the problem with the LLM model.
>> Gotcha. So, there's no moes in LLM.
>> Yes. hyperscalers they have I guess they
have diversified business models so
there's
>> and they have modes but they're
dependent upon the LLMs in their cloud
businesses that's their weakness right
now
>> so okay so there's kind of a argument
for hyperscalers for and against having
a mode you kind of in some ways there's
the scale and the cost and the barrier
to entry mode of of the investment and
then there's also the dependency on the
people that are buying
>> that have no modes
>> yes
>> that's the problem
>> interesting Okay.
>> And the other and the other problem with
the hyperscalers this may be temporary
but then again maybe it's not is you
know Microsoft Amazon Google 3 four
years ago and way prior to that these
companies were incredibly profitable but
even more importantly they just threw
off cash like crazy. I mean so much cash
they didn't even know what to do with
it. So they just bought back stock
because they literally didn't have any
enough investments to pour back into
their own businesses. Today, because of
the incredible amount of money that
they're that they're spending on these
data centers, their cash flow is gone.
>> I noticed that.
>> And in some cases, negative
>> negative now. Yeah. Yeah. Very little.
>> I mean, Google raised equity capital 85
billion. I mean, if you had said to me a
year a two years ago that that hey,
Steve, I'm gonna make a prediction.
Google,
which hasn't raised capital since it
went public, is going to raise 85
billion not in debt, in equity capital.
I'd have said, "You're out of your mind.
You're insane." Like like what are you
talking about? They they create 85
billion in cash in like overnight like
why what would what would possess them
to raise equity capital? Well, world
changed.
>> It's a very dramatic shift. Uh I I feel
you know as you know an investor that's
held Google for probably eight years
right the company that I hold now is
very different to the company that
>> and that's an interesting point we've
seen the market get a little bit jittery
with the amount of spending that's
happening there could be a payoff maybe
there's not you
>> by the way let me just jump you for one
second let's go back to Oracle
>> okay
>> because after that I I didn't finish
after Oracle Um every people said that
50% of Oracle's RPO the the backlog is
from open AI. the stock which had gone
from 230 to 330 over the next 2 3 months
went to 200 and today it's 150 and
what's fascinating fascinating
>> is Oracle just reported and the numbers
were pretty good
>> and the stock was up four or five% after
hours
>> and was up 7% at the open and closed
down on day
>> right
>> and I was and and there was no news so I
don't have like I don't have like a news
explanation like nothing happened but
>> clearly people are very nervous about
Oracle because Oracle got downgraded and
its debt rating is like triple B minus
by S&P which is like I think maybe just
one level above junk.
>> So people are nervous about Oracle and
how much debt they have.
>> Well, it seems investors are nervous
about all of these hyperscalers now that
are investing literally hundreds of
billions like
>> hundreds
>> hundreds of billions. It it's just it's
insane. staggering. It's the numbers and
you know the numbers are just so big.
>> I think the number that I heard this
year is that if you just look at the
hyperscalers, they will spend $700
billion on AI capex this year.
>> It's like that's such a huge number.
It's hard to even get your mind around
it.
>> It's so enormous.
>> I'm interested in your perspective on
what Michael Bur has been saying where
he's concerned that the data centers are
taking too long to come online. They're
buying so many chips. He his opinion is
the chips become obsolete way faster
than the depreciation schedules.
>> I I I understand his argument. So So let
me give his it's its due first. Yeah.
>> What he pointed out last year, I think
in November was that the hyperscalers
had changed the depreciation schedule
of the chips from 3 to four years to
like five to six years. And if you did
like a I can't remember exactly what the
calculation but but it's an it's an
enormous increase in profitability just
from the change in that accounting
because by by changing right it's like
click by by um by changing your
depreciation schedule from three 3 to
four years to 5 to 6 years by definition
your depreciation expense which you
report is going to be lower all other
things being equal. He also said that,
you know, there's so many new chips
coming that they become obsolete. Where
I think he's wrong for the moment is
that there is such demand for chips
right now that there's still huge demand
for the older chips whose price has gone
up with all the other chips,
>> right?
>> So I I I think with all due respect to
Michael, I think his argument is too
academic.
>> Okay? Like put this way if AI succeeds
because anthropic and open AI you know
grow like crazy and the hyperscalers do
well etc etc it's not going to matter if
the depreciation schedule changed from 3
to four years to 5 to six years
>> right
>> at the same time if open AI fails and
and the whole chain goes in reverse
we'll have a massive correction which
has nothing to do with the depreciation
schedule I don't I mean I think what
he's deep down what he's is trying to
point out is maybe there's something
wrong here, but I don't think what the
thing that he's pointing to as being
wrong is what's going to is is important
enough,
>> right? There's bigger factors that play
both directions in both
>> much bigger factors.
>> Okay. Interesting. So, we've spoken
about no moes, we've spoken about China
coming in potentially being competition.
Another headwind that I've been trying
to wrap my head around more is is the
power element as well
>> because this is another one of those big
things that we're talking about earnings
and chips and this and that.
>> But when I started to look at power, I I
think it was Elon Musk's interview with
the economist that opened my eyes up to
it. He said China has a chip problem.
The US has a power problem.
>> He's right.
>> However, in his view, China can solve
its chip problem. might take some time,
but a harder one to solve is the power
problem because power is physical
infrastructure. It takes a long time.
>> Correct.
>> I don't know if I have the expertise or
the understanding to know how big of a
restraint or a bottleneck power in the
United States is actually going to be.
>> Get in line. Nobody Nobody knows,
>> right?
>> I mean, I keep looking, you know, I
there are people who say it's a b that
things are slow. There are other people
who say things are fine. I can't I can't
nail it down yet.
>> Right. Okay. I mean, I do know that the
companies that are involved with power
>> are doing great.
>> Like Genova, for example, and that
stock's gone nuts. You know, I'll pat
myself a little bit on the back. I
bought that stock really early. Oh,
really?
>> But but I I bought it because the sell
side analyst I'm very friendly with told
me I should buy it and I just took a
flyer on it.
>> But um
>> for those that don't know Geneva told
me,
>> let me tell you, it's very interesting.
So GE used to be composed basically of
three massive divisions. healthcare,
>> aerospace where they basically make the
jet engines for planes and then they
service them
>> and then call it energy. If you ever saw
a jet engine
>> and looked at at a gas turbine, which is
what goes into a utility that creates
electricity, they look exactly the same.
It's just that the gas turbine is much
bigger.
>> Yes.
>> But it's basically the same technology.
So the energy division of of GE
makes gas turbines. They have all this
electrical equipment that they sell and
then they have a wind division which
does terribly.
>> Now this should show you how like fast
the world can change. The the energy
division was created when I think around
2015 or so. GE bought a company in
Europe called Olam. Now Olm did was an
energy company that also created gas
turbines and GE had a business that
created gas turbines. So they mushed
them together just in time for the
entire gas turbine business to fall
apart,
>> right?
>> And this is why IML lost his Jeff Immel
who was the CEO of GE finally lost his
job because that was like enough
already. So eventually all three
divisions got spun out. So there's GE
healthcare. I think its symbol is GE.
>> Okay.
>> And there's the energy division which is
called GE Vernova which is GEV. And then
there's GE which is the aerospace
division.
>> Gotcha.
>> A year before [snorts] GE Vernova got
spun out. So that would have been like
2023
maybe or 2022. If you were to read
sellside reports
upon about the industry, the energy
business was so bad
that they ascribed negative value to G
to to Vernova. Negative value that it
was worth negative. I think when one guy
wrote it was worth negative3 billion.
>> Oh my gosh.
>> In terms of a sum of the parts analysis
>> right
>> now what's happened is even prior to the
whole data center thing electrical
production in the United States finally
started to increase for the first time
like in 15 years. Now add on top of that
the
data centers and you're talking about US
electricity growing 3 to 4% per year.
Now that may not sound like such a huge
number but 3 to 4% off of the base of
the United States is the equivalent of
like two large cities.
>> Okay. It's a lot.
>> It's huge.
>> Yeah. You know, a company like GE
Vernova has backlogged like two 20 35
that that's how crazy things are
>> because this is how these data centers
are being powered. It's with these gas
turbines, right?
>> Mostly
>> mostly
>> and there's some alternatives. People
are talking about nuclear and they're
and there's a company called Bloom
Energy which makes its own little
turbine
>> that that you could hook up to a to a
data center, but most of it's going to
be through gas turbines. M well that's
what um Elon had to do with the um
Colossus data center that he built in
Memphis. The grid was too slow. It was
not ready. So he he ended up getting 35
of the portable gas turbines,
>> right? And hooked it up to his hooked
up.
>> Hooked it up. He created his own mini
power center like on site right next to
Okay.
>> So So most most of GNOVA is these um
>> well it's the gas turbines. It's all the
electrical I mean think about it. I mean
there's You know, you're not just when
you're building a new utility plant, it
ain't just turbine. There's all this
other electrical equipment that's got to
get hooked up. They make that too. And
the wind business will always, I think,
be a crappy business. And and that that
so what,
>> right? Okay. Very interesting. Very
interesting. But you would say the thing
to look out for in Genova's case is the
gas turbines. Is that the core of that
business?
>> Yeah. I mean, that's the core. And you
would just want to look at the orders.
>> Yes.
>> Which I think in the last quarter up
like 85%. Something insane. I
>> I mean they I mean there's those gas
turbines like in the room that we're in.
It's like is it's like five of these
rooms combined is how big these things
are. They're huge. They're I mean it
takes years to build them.
>> Yes. Well, that's what I was going to I
think I read something that their
backlog is stretching out to past 2030
or something like it is
>> which is just
>> Well, because people want to they want
to line it up as much as they can. M but
is that even more of a uh an argument
for this power problem if [laughter]
people are making orders now we want
these turbines now and hang on well
we've got 2030 you want
>> I I just don't know I really don't know
I don't have enough information
>> yeah I um I can't remember who it was
that you interviewed the man that knew
uh it was about power but I found that
was a really good interview I might
leave it linked um on screen right now
but I I thought that was a really really
good explanation okay so we've covered a
lot
headwinds when it comes to AI. I think
you you went on the record saying that
if you try and predict what's going to
happen, you're a fool. So, don't don't
try and predict it. I think there are a
lot of people out there that feel
compelled to look at these AI plays to
to look into the realm of AI. If you're
if someone comes to you and says, "Oh,
look, Steve, I really got to get in on
AI somehow." What are what are some of
the maybe safer ways to play AI? And
what's what would you say are the
high-risk ways to play AI? Talking about
just investing in in stuff.
>> I mean, I would play I wouldn't invest
in an LLM because I just think, as I
said, there's no I would not. I would
not
>> because there are no moes.
>> Yeah, that makes sense.
>> I might be a little wary of the
hyperscalers at this point just because
their businesses have they've lost all
their cash flow.
>> But I would be looking at the companies
that are getting that cash flow,
>> right?
>> So, you know, that would be Nvidia. you
know, maybe you you'd want to own
Micron, GE, Verova, um, Arista Network,
Cisco, and then if you want to get into
the industrial side, you could talk
about like an Eaton, which could is
electrification company. That's what I
would
>> So, it's more it's more picks and
shovels.
>> Picks and shovels,
>> right? As opposed to the flashy software
side,
>> right?
>> Okay.
>> The software, you know, the whole
software industry to I mean, I'm sure
you've heard the word SAS apocalypse.
>> I have. Um, [laughter]
and I I I I all I know is there will be
software companies that will have
problems
>> because, you know, take this new Agentic
AI um, Muse, I think it's called, that
Meta put out. You know, if I want to
book
a flight, I say to my muse, oh, that's
good. I say to my muse,
I want to book a flight to Miami on such
and such a date.
book me in the best hotel in Bickl.
>> Okay. And it goes and does it. Well, how
does it do it? It goes on all the travel
sites
and finds the best price and books it.
>> Mhm.
>> Well, that kind of makes the travel
sites worth less because you're not
going to you're not going to bookings or
travel velocity or what whatever
directly anymore.
>> You're not their customer anymore. your
AI is
>> you're AI my AI agent is my customer he
and he does the work
>> and the sidebar ads don't work on that
>> so stuff like that I think stuff in the
payment world could get dicey but on the
other hand you know software that's
deeply embedded in enterprises is
probably okay
>> well that's what I was going to ask you
it sounds like the most important thing
to look at is the switching mode and how
how resilient
>> how resilient is it okay I mean you know
for bookings what's the switching mode
you know I go to I go on the bookings
website and I book a trip so now I don't
go on the bookings website. I my agentic
AI finds just the best deal.
>> So that kind of makes the the travel
online
companies worth less. I think it's a
little early, but I think that's a
possibility.
>> Yeah. Okay. So I I guess another
argument that I've heard and I'm
interested to hear your overarching
thoughts on this around AI is people are
very fast to liken it to 1999,
>> a techbubble 2.0. Oh, no. You know,
that's that's what the media will say,
>> right?
>> I'm very interested in what your
thoughts are on this.
I have my own opinion, but I'm
interested to hear what you think. We're
in the same setup. New technology,
speculation in financial markets,
>> similar setup. Is it different this
time? Is there anything fundamentally
different?
>> I I don't know if it's different or not.
I think it's too early. I mean, if open
AI or anthropic fail, you'll have a real
correction and then the next generation
of people will come up and pick up the
pieces. I don't know if that's going to
happen or not. So, I I just don't know.
>> Fair enough. Going back to the investing
argument, I I'm actually interested
because I didn't ask you last time and I
had some subscribers that are interested
in understanding how you actually go
about your investing, not stocks, not
what stocks you're picking or anything
like that, but when it comes to the Real
Eman playbook, what is the Real Eisman
playbook? How do you analyze companies?
Is it do you stick within a circle of
confidence? Do you go down rabbit holes?
Do you look at certain financial metrics
that you really love to see or not?
>> Well, a couple of things. I'm very
storyoriented.
>> Story. Okay.
>> I am not a quote unquote value player, I
think.
>> Okay.
>> You know, stocks are cheap. They're
probably cheap for a reason. Okay. You
know,
>> but I can't see you being someone that
will grossly overpay for something
either.
>> I I see you as personally I see you as
very rational. You know, I I mean, I
would have loved to have owned
Palunteer, but I won't buy it now
because it's so expensive.
>> Yeah.
>> Um,
>> so story but rational.
>> Very story. Story but rational.
[laughter]
>> Okay. Is there anything uh are there any
kind of uh metrics on your checklist or
anything that you love to look at that
might be a red flag? I'm just interested
to see like what you really look for. Is
a moat like a must-have for you or
>> Not necessarily. I like a moat.
>> That's why I own Moody's for example. Um
that's why I own Visa.
>> Mhm.
>> But um it's not a complete requirement.
So no.
>> Is there anything that you particularly
hate to see in a company? What's what's
what are some things that will instantly
turn you off?
>> Management selling stock.
>> Okay.
>> I generally don't like cyclical
companies.
>> Okay.
>> Because then you're just predicting the
economy. And I mean there are
exceptions, but I I I like companies
that have a real story with real growth
tailwinds,
>> right?
>> That's what I like.
>> Okay. Interesting. Hey, do you mind if I
finish off by asking you some questions
from the audience? Sure. Is that all
right?
>> All right. I had a quick screen, but I
might have forgotten some. [laughter]
>> All right, let's Oh, this is a really
interesting one. I did want to get your
opinion on this. US debt. This is such a
a an interesting topic and it's very
very very highly covered. So it's at $40
trillion now. The average interest rate
on it has gone from 1.77% in 2020 to
3.45% today. The interest expense has
risen from 523 billion a year to now
1.22 trillion. Is that something
investors need to be genuinely worried
about? Is there a real risk of a debt
spiral in the future?
>> I mean all the things be equal. I wish
the deficit was smaller.
>> Y
>> um I I have my doubts about a debt
spiral. Number one, we are the reserve
currency of the world. But maybe even
more importantly, US treasuries are the
financial system of planet earth. So
just for example,
banks all over the world do something
called repos where they lend to each
other overnight. They do it through
overnight treasuries.
So, as long as the US Treasury is the
backbone of the financial system of the
world, I tend not to worry about the
deficit too much, although I'd like it
to be smaller. If there was an
alternative, we'd be in trouble.
>> Okay?
>> But there is no alternative at this
point.
>> Let me ask you this. The Fed just raised
rates for the first time in 3 years. Are
rates uh likely to be a showstopper for
the market and in particular the AI
narrative? The rate to look at is the
10-year.
>> It's long the long-term rates, not the
short-term rates that the Fed does
because that's what people borrow.
>> Okay?
>> You know, the Fed is just
>> the Fed funds rate is the rate at which
the Fed lends to banks overnight.
>> Okay?
>> You don't have access to that. Neither
do [laughter] I.
>> Um to the side.
>> Yeah. So,
you know, just today, for example, the
markets rallied because despite the Fed
raising rates, the 10-year yield went
down.
I'm getting the feeling that 5% is sort
of the Rubicon for the market.
>> And um as long as we're below that,
we'll probably be okay. But if something
were to happen and and we blow through
that, I think we get a correction.
>> Okay. Because it's around
>> that's just my guess. I actually thought
originally the number was 4 and a half%
and I was wrong.
>> Okay.
>> But five feels more.
>> Do you know where it is now? It's around
there.
>> It's 4.98.
>> 4.98. Okay.
>> But it was over 5% yesterday. Yes.
>> And it's come back down. People are
watching every tick.
>> Yes. Interesting. I'm interested to hear
Steve's thoughts on Here we go. rising
yields of long-term treasuries. Is Scott
Bessant's buyback plan really designed
to increase liquidity in older long-term
bonds? Or is the government trying to
manipulate long interest rates to ease
their interest problem?
>> The latter.
He's trying to buy long long-term
treasuries to bring rates down to ease
the cost of of money for the United
States of America. He's failed miserably
at this point. You know, rates are
higher than when he made his
announcement. I have a suspicion that
he's going to come with something else
because because well, he he he announced
6 billion. 6 billion is nothing. I mean,
it's a $40 trillion deficit.
>> That's that was my thought.
>> So, I I I don't think he's an idiot. So,
I think he's going to come with
something else. What else that is, I
don't know.
>> Okay. So, a different plan of attack to
do the same thing. Yes. Ah, okay. Okay.
I've always been skeptical about
precious metals, but Steve's recent
discussion with Porter Collins and
Vincent Daniel made me second guess
that. I would like to know if he has any
conflicting feelings about precious
metals, or is he still firmly opposed to
the asset class?
>> I'm not opposed, but I don't I've never
owned it.
>> Y
>> I've never owned it. I It's not
something that has ever really enticed
me one way or the other. Similar
thinking to Warren Buffett. It just sits
there and looks right.
>> Sits there. Does nothing.
>> Does nothing. It's not productive. It
>> It has value because people say it has
value.
>> Okay.
>> That's all. Doesn't pay you an interest
rate.
>> Similar argument, I'm guessing, to
Bitcoin and anything else that sits
there in
>> Oh, definitely.
>> Baseball cards, blah blah blah, whatever
sits there.
>> Well, Bitcoin is worse.
>> Bitcoin is worse. Yeah,
>> Bitcoin is worse because it trades
inversely to its own thesis.
>> Yes, I have noticed that. That is quite
strange. So, so for those for your
viewers, what I what I mean by just to
explain what I mean by that is people
like if you went to a Bitcoiner
>> and you said, "Dude,
>> why do you want Bitcoin?" The answer you
would invariably get is that that fiat
currency, which is government
currencies, has been debased, inflation
is coming, and you want to hedge against
this, so buy Bitcoin.
>> Okay, that sounds reasonable. The
problem is that if that were the case,
on days where people worry about
inflation, rates are going up, and the
stock market goes is down, Bitcoin
should be up. And on days where NASDAQ
is up like crazy and rates are down,
Bitcoin should be down. But it does the
opposite.
>> Yes.
>> So, so you know, you you say that
Bitcoin is going to go up when because
when the sky is blue and then the sky is
blue and it goes down, you know, why do
I own it? You have no thesis. It seems
to be just a speculative asset.
>> It's just like it's a way to speculate
about speculating.
>> Speculate about speculating. I like
that. All right, let me ask you this.
Dear Steve, you seem to be very much
centered on the US stock market. Have
you ever tried to broaden your investing
or trading horizon geographically? Do
you have any interest in companies held
outside the US?
>> Great question. When I used to run my
hedge funds, I used to invest overseas.
>> Mh.
>> And I found that there was no night and
there was no day.
>> Okay. So for the last many many years,
all I do is the US and I'm perfectly
happy. There's plenty to do in the US. I
don't feel the need to invest overseas.
>> Fair enough. Plenty of opportunities
here. I like it. What's his view on when
all these wars would end? I guess
particularly the Iran war. Do you see
inflation coming down anytime soon?
>> I have no more insight into the war than
anyone else, so I can't answer the
question.
>> Fair enough. Well, I think that is just
about all we've got. Is there one more?
Is there one or a set of numerical
indicators, whether related to interest
rates or inflation or unemployment or
otherwise, that Steve could see as being
the tipping point for the US to take its
medicine with cutting benefits or wash
spiking rates up or whatever he thinks
that medicine might be? I've seen I've
seen it said that oil will rise until
stocks fall, meaning that the US won't
get out of Iran until stocks really take
a beating. But this is a much broader
question about getting the debt back
well under control. I guess we kind of
touched on that with the kind of touch.
I mean, all I would say is that's a
total political question,
>> and there's no political appetite in
Washington right now to cut the deficit
>> a dollar
>> by either side.
>> We'll see where that goes.
>> I think that's just about how we
finished our last [laughter] our last
interview. And I was like, on that
cheery note, so again, on that cheery
note, Steve, thank you very much for for
coming on. For those that don't know,
well, we talked about it earlier, but
The Real Eisman Playbook is uh is what
you're currently working on. That's your
podcast. Can you tell us a little bit
more? What can people expect from that?
It's on YouTube. I guess you can get it
on podcast platforms as well.
>> Well, we do two two free podcasts a
week. So, one is an interview. So, and
then the other one is a market rap where
on Friday I put out like a summary of
the whole week and then if you're
willing to pay for the payw wall on
Substack, we do an additional podcast
which is sometimes an interview. This
week was part one of two-part master
lecture of how to analyze banks.
>> All right.
>> Yeah. I have to check
>> if anybody who ever But you have to
subscribe.
>> Okay, I will subscribe. [laughter] No
free lunch.
>> No free lunch there city here.
>> I will see.
>> Yeah, but if you want to know how to
analyze banks,
>> go there.
>> That's where you should go.
>> Awesome, Steve. Thank you very much for
Thank you very much. Appreciate it.
>> Great. Bye.
>> Yes,
you're the man now, dog.
Interactive Summary
Ask follow-up questions or revisit key timestamps.
Steve Eisman discusses his concerns regarding the current AI investment boom, highlighting significant concentration risks, the lack of "moats" in the LLM sector, and the immense financial dependency between chip manufacturers, hyperscalers, and AI model creators. He also covers the power infrastructure bottleneck, his personal investment philosophy, and his views on US debt and speculative assets like Bitcoin.
Suggested questions
4 ready-made promptsRecently Distilled
Videos recently processed by our community